Terris Recommends 16,400+ monthly visitors Finance & Insurance
10 Best Insurance Brokers in Singapore (August 2026)
My editorial picks of the 10 best insurance brokers in Singapore for 2026, decoding broker vs tied agent. Compared on type, model and what it means.
This guide is part of Terris Recommends, my researched, hands-on picks of the best local businesses and services in Singapore. Every recommendation is researched and ranked by me.
See all recommendationsUnderstanding insurance brokers in Singapore starts with one question that clears up most of the confusion: who does the person actually work for? A tied agent represents a single insurer and sells that company's products. An insurance broker represents you, the client, and shops your risk across many insurers to find the right cover at the right price. That difference matters most when you need to claim.
Brokers are usually paid a commission that is built into the premium, so engaging one does not normally cost you more than going direct, and you gain an advocate who negotiates on your behalf. The market splits into local general brokers, SME and employee-benefits specialists, global corporate brokers, digital comparison platforms and expat health specialists. I will explain how to choose and how they are paid, then give you my picks.
This is part of my Terris Recommends Finance and Insurance series, and it is general information, not insurance advice. It pairs with my guides to financial advisers and will-writing services.
Beyond the brand, here is what actually matters when you choose a broker.
- Who they represent. A broker should represent you, not an insurer, and place your business across the market. Ask them directly whom they act for and how many insurers they work with.
- MAS registration. Verify the broker is a registered insurance broker on the MAS Financial Institutions Directory. Broking is a regulated activity here.
- How they are paid. Usually a commission inside the premium, sometimes a fee for complex commercial work. It does not normally cost you more than going direct, but ask so you understand any conflicts.
- The right segment. Personal lines, SME packages, large commercial and specialty risk, employee benefits, or expat health are different specialisms. Match the broker to your actual need.
- Claims support. The real value of a broker shows at claim time, when they advocate for you against the insurer. Ask how they handle claims before you sign up.
One tip: for a business, a broker who understands your industry's specific risks, from work injury to professional indemnity, is worth far more than the cheapest quote.
| Broker | Type | Best for |
|---|---|---|
| AWG | Local, personal and commercial | Both personal and business |
| Times Insurance | Local general broker | An established all-rounder |
| David Ho | SME and employee benefits | Group health and WICA |
| Marsh | Global corporate broker | Large and complex risk |
| Howden | Global specialist broker | SME and specialty lines |
| Aon | Global broker | Risk and employee benefits |
| eazy | Digital broker | Compare and buy online |
| Insurance Market | Digital comparison broker | Personal-lines comparison |
| SingSaver | Digital comparison | Mass-market compare |
| Pacific Prime | Expat health specialist | International health cover |
Understanding the cost of a broker is mostly about how they are paid rather than a fee you see.
| Model | What it means | Good to know |
|---|---|---|
| Commission from insurer | Built into the premium | Does not normally cost you extra |
| Fee for advice | Charged for complex commercial work | Agreed upfront |
| Digital comparison | Commission on policies bought | Free to compare |
Because a broker is usually paid the same commission the insurer would otherwise keep, using one to shop the market rarely costs you more than buying direct, and often finds better cover. For large commercial risk, a transparent fee arrangement can be cleaner, so ask how the broker is remunerated.
That breadth means one broker can handle your household and your business. For a small business owner who wants both sides covered by a single, established broker, it is where I would start.
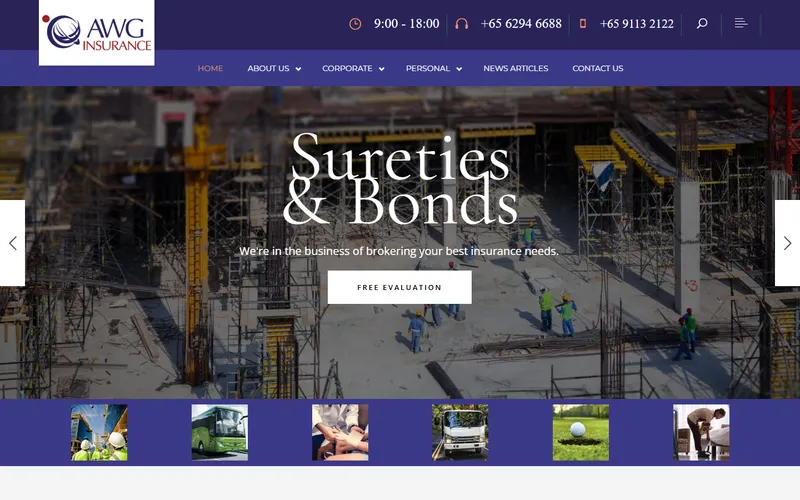
- Best known for
- Genuinely covering both personal and business insurance
- Type
- Local, personal and commercial
- MAS registered
- Yes, registered insurance broker
- Website
- awginsurance.com
That longevity brings deep insurer connections and claims experience. For a business or individual who values a long-standing, dependable local broker, it is a strong choice.
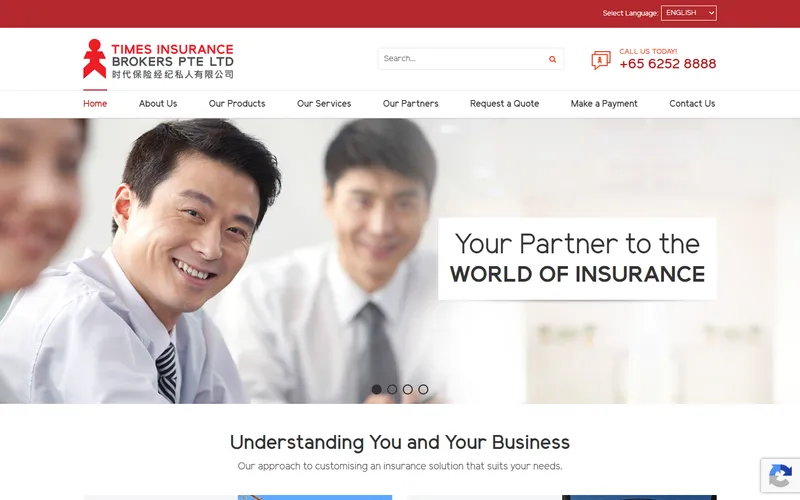
- Best known for
- One of the oldest local general brokers, since 1976
- Type
- Local general broker
- MAS registered
- Yes, registered insurance broker
- Website
- timesinsurance.com.sg
That focus on the employee-benefits and SME side, with a single point of contact who knows your account, is exactly what a start-up or SME wants rather than a call-centre. For business protection and staff benefits, it is my recommendation.
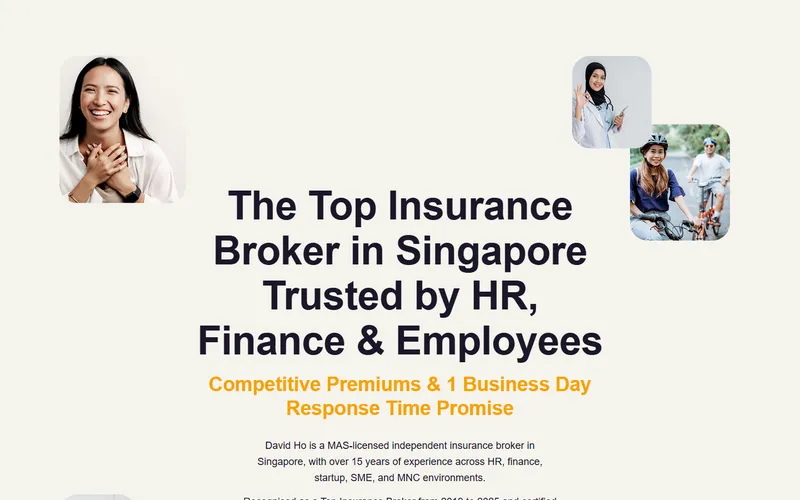
- Best known for
- SME cover and employee benefits with personal service
- Type
- SME and employee-benefits broker
- MAS registered
- Yes, licensed independent broker
- Website
- davidho.sg
For a mid-sized or large company with serious or specialised exposures, that depth is hard to match locally. It skews corporate rather than walk-in retail, so it is the pick when your risk is substantial.
- Best known for
- Large, complex corporate risk
- Type
- Global corporate broker
- MAS registered
- Yes, licensed broker
- Website
- marsh.com
That blend of SME accessibility and specialty depth sets it apart from purely corporate brokers. For a business with a specific or technical risk to place, it is a strong choice.
- Best known for
- SME cover plus specialty lines
- Type
- Global specialist broker
- MAS registered
- Yes, MAS-regulated intermediary
- Website
- howdengroup.com
For a larger employer thinking about its benefits programme as a strategic tool rather than a commodity, Aon's human-capital angle is genuinely useful. It is a corporate-tier choice for benefits-led needs.
- Best known for
- Risk and strategic employee benefits
- Type
- Global broker and human capital
- MAS registered
- Yes, licensed broker
- Website
- aon.com
That combination of a slick digital experience and a genuine broker model, covering both personal and business lines like public liability and work injury, is a nice middle ground. For someone who wants to compare online but still have a broker behind it, it is a strong choice.
- Best known for
- A digital portal that represents the client
- Type
- Digital broker
- MAS registered
- Yes, MAS-regulated broker
- Website
- eazy.com.sg
Being MAS-registered, it offers the transparency of comparison with the backing of a broker. For an individual who wants to shop personal insurance efficiently and objectively, it is a handy platform.
- Best known for
- Comparing personal insurance with broker backing
- Type
- Digital comparison broker
- MAS registered
- Yes, registered broker
- Website
- insurancemarket.sg
It is more comparison platform than advisory broker, so it suits straightforward cover rather than complex needs. For an individual who just wants to compare and buy a simple policy online, it is a convenient choice.
- Best known for
- Fast mass-market insurance comparison
- Type
- Digital comparison
- MAS registered
- Holds a brokerage licence
- Website
- singsaver.com.sg
With two decades of experience and a global footprint, it understands the cross-border health-cover needs of expats and international companies. For an expat or a firm insuring international staff, it is my recommendation.
- Best known for
- International and expat health insurance
- Type
- Expat health specialist broker
- MAS registered
- Yes, insurance broker
- Website
- pacificprime.sg
I looked at whom each broker represents, MAS registration, how they are paid, their segment, and their claims and service reputation. I deliberately spread the list across local general brokers, SME and benefits specialists, global corporate brokers, digital comparison platforms and expat health, because the right broker depends entirely on what you are insuring.
This is general information, not insurance advice, and details are checked when I publish and revisited as things change. Always verify a broker is MAS-registered, and ask how they are paid and how they handle claims, before you engage them.
An insurance agent, or tied agent, represents one insurance company and can only sell that company's products. An insurance broker represents you, the client, and can place your business across many insurers to find suitable cover and competitive pricing. The practical upshot is whose side they are on: a broker is your advocate and will negotiate for you, including at claim time, whereas an agent works for the insurer. For anything beyond a simple single-product purchase, a broker's independence usually works in your favour.
Usually not. Brokers are typically paid a commission that is built into the premium, the same commission the insurer would otherwise keep or pay a direct channel, so using a broker to shop the market rarely costs you more than buying direct, and it often secures better cover for the price. For large or complex commercial risk, a broker may charge a transparent advisory fee instead, which is agreed upfront. Ask any broker how they are remunerated so you understand the arrangement, but do not assume a broker is more expensive.
For a small business, a broker is often worth it because business insurance is more complex than personal cover, spanning work injury compensation, public liability, professional indemnity, property and employee benefits, and the right structure depends on your industry. A broker who understands your sector can identify gaps, place cover across insurers, and advocate for you at claim time, which is hard to do yourself. For a very simple micro-business, a direct package may suffice, but as you take on staff and contracts, a broker like David Ho or a general broker becomes valuable.
Yes. Insurance broking is a regulated activity in Singapore, and brokers must be registered with the Monetary Authority of Singapore, appearing on the MAS Financial Institutions Directory under categories such as registered or exempt insurance broker. You can and should verify a broker's registration on the directory before engaging them. This regulation gives you recourse and standards to rely on, and checking takes only a couple of minutes, so never work with a broker you cannot find on the MAS register.
Anyone searching for insurance brokers in Singapore is being careful, and they will check whether you look legitimate before they pick up the phone.
Licence details, named people with real faces, plain explanations instead of jargon. Financial firms lose enquiries to sites that feel anonymous, because being anonymous is exactly what the reader is worried about. I build websites for Singapore finance and advisory firms that make the credentials easy to verify, and the SEO to reach people at the moment they start looking.
If your site was built once and never touched again, get a quote and I will tell you what is costing you enquiries.
The best insurance broker in Singapore is the one that represents you and specialises in what you are insuring, so match the broker to the need: AWG or Times for an all-round local broker, David Ho for SME and benefits, the global firms for complex commercial risk, and Pacific Prime for expat health. Verify their MAS registration, and remember a broker usually costs you no more than buying direct while giving you an advocate.
Get the right broker and you have someone on your side when it matters most, at claim time. This guide is general information, not insurance advice.
A broker sells you cover. Whether you need that cover, and how much, is a planning question, which is what my guide to the best financial advisers in Singapore covers. Once the policies are in place, name who gets them: my will-writing guide explains why the policy nomination and the will are two separate jobs.
If you run an insurance or professional-services business and your website is not bringing in enquiries, that is what I do. I design websites for businesses across Singapore. Get in touch for a free consultation.