Terris Recommends 16,400+ monthly visitors Finance & Insurance
8 Best Financial Advisers in Singapore (August 2026)
My editorial picks of the 8 best financial advisers in Singapore for 2026, decoding tied vs independent vs fee-only. Compared on model and typical cost.
This guide is part of Terris Recommends, my researched, hands-on picks of the best local businesses and services in Singapore. Every recommendation is researched and ranked by me.
See all recommendationsChoosing a financial adviser in Singapore is really a question of whose interest the advice serves, and that is decided by two things most people never check: whether the adviser is properly licensed, and how they are paid. Get those straight and you can cut through the marketing quickly.
Everyone who gives financial advice here must be licensed by the Monetary Authority of Singapore, and you can verify it yourself. Then there is the independence and payment ladder: a tied agent sells one insurer's products, an independent adviser uses many providers but is often still paid by commission, and a fee-only adviser charges you directly and rebates commissions, which is the cleanest position on conflicts of interest. I will show you how to verify and choose, then give you my picks.
This is part of my Terris Recommends Finance and Insurance series, and it is general information, not financial advice. It pairs with my guides to insurance brokers and will-writing services.
Before you compare firms, check these things, in this order.
- MAS licence. Verify the firm on the MAS Financial Institutions Directory and the individual adviser on the Register of Representatives. This is non-negotiable and takes two minutes.
- How they are paid. Commission from products, a fee you pay directly, or a mix. A fee-only adviser has the least incentive to push a particular product. Ask for the fee model in writing.
- Independent or tied. A tied agent offers one company's products, an independent adviser can compare across many. Independence widens your options, though it does not by itself remove commission incentives.
- Specialisation. Retirement and CPF or SRS planning, expat and cross-border, high-net-worth wealth, or protection. Match the adviser to your actual need.
- The advice, in writing. A proper adviser gives you a documented recommendation with the reasons and the costs. Read it, and be wary of pressure to sign on the day.
One tip: the government's MoneySense site explains the difference between tied, independent and robo-advisers, and is a neutral starting point before you meet anyone.
| Firm | Model | Best for |
|---|---|---|
| Providend | Fee-only, independent | Conflict-free advice |
| Financial Alliance | Independent (IFA) | The largest IFA firm |
| IPP Financial Advisers | Independent FA | An established name |
| GEN | Independent FA | CPF and retirement planning |
| Synergy | Independent (IFA) | A wide product panel |
| Ascenta Wealth | Fee-based, expat | Cross-border planning |
| GFC | Expat FA | UK pension transfers |
| PromiseLand | Independent (IFA) | Expat advisory |
Cost depends on how the adviser is paid. Here is what to expect in 2026.
| Model | Typical cost | Good to know |
|---|---|---|
| Commission-based adviser | No upfront fee to you | Paid via product commissions |
| Fee-based advisory | An advice fee plus some commission | Partly fee, partly commission |
| Fee-only financial plan | Around S$2,000 to S$8,000 | Commissions rebated, cleanest |
| Ongoing wealth management | Around 0.5 to 1 percent of assets a year | For larger portfolios |
Commission-based advice feels free but is paid for inside the products you buy. A fee-only arrangement costs you directly but removes the incentive to recommend high-commission products, which for larger or complex situations often works out better value.
It focuses on holistic wealth and retirement planning for people with meaningful assets to manage. For a client who wants advice they can trust to be free of product bias, it is my top recommendation.
- Best known for
- Conflict-free, fee-only wealth advice
- Model
- Fee-only, independent
- MAS licensed
- Yes, verify on the MAS directory
- Website
- providend.com
It offers a fee-based financial planning option alongside its usual model, so you can choose how you pay. For a client who wants a large, established independent firm with real breadth, it is a strong choice.
- Best known for
- The largest independent adviser, with a fee-based option
- Model
- Independent financial adviser
- MAS licensed
- Yes, verify on the MAS directory
- Website
- fa.com.sg
It also runs a dedicated expat advisory division for cross-border clients. For someone who values longevity and scale in their adviser, it is a dependable, well-known choice.
- Best known for
- One of the oldest and largest advisory firms
- Model
- Independent financial adviser
- MAS licensed
- Yes, verify on the MAS directory
- Website
- ippfa.com
That focus on the CPF and retirement side of things is genuinely useful for Singaporeans planning the long term. For a client who wants to understand their options rather than be sold to, it is a refreshing choice.
- Best known for
- Education-led CPF and retirement planning
- Model
- Independent financial adviser
- MAS licensed
- Yes, verify on the MAS directory
- Website
- gen.com.sg
It covers personal, corporate, general insurance and high-net-worth planning. For a client who wants an independent firm that has invested in technology as well as range, it is a strong option.
- Best known for
- A wide product panel with a digital platform
- Model
- Independent financial adviser
- MAS licensed
- Yes, verify on the MAS directory
- Website
- synergy.com.sg
That combination of a fee-based approach and genuine cross-border expertise is hard to find. For an expat with assets and obligations in more than one country, it is my recommendation.
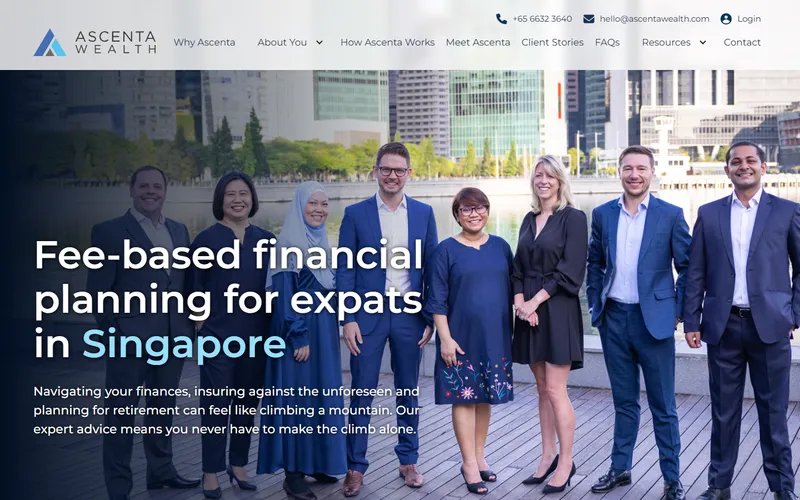
- Best known for
- Fee-based cross-border planning for expats
- Model
- Fee-based, expat specialist
- MAS licensed
- Yes, verify on the MAS directory
- Website
- ascentawealth.com
It positions itself away from sales tactics, which matters in the expat advisory space where some firms lean hard on commission products. For an expat, particularly a British one weighing a pension transfer, it is a knowledgeable choice.
- Best known for
- Expat planning and UK pension transfers
- Model
- Expat-focused financial adviser
- MAS licensed
- Yes, verify on the MAS directory
- Website
- gfcadvice.com
For an expat who wants an independent firm that gives a written fee breakdown before engagement, it is a solid choice. As always, verify the firm and your specific adviser on the MAS directory first.
- Best known for
- Expat advisory with transparent fee breakdowns
- Model
- Independent financial adviser
- MAS licensed
- Yes, verify on the MAS directory
- Website
- promiseland.com.sg
I looked at licensing, how each firm is paid, whether it is independent or tied, its specialisation, and its track record. I deliberately spread the list across fee-only, independent and expat-focused firms, because the right adviser depends heavily on your situation and how you prefer to pay. I left out tied, single-insurer models, and noted where a firm is not fully independent.
This is general information, not financial advice, and details are checked when I publish and revisited as things change. Always verify a firm and your adviser on the MAS directory, and read the written recommendation and fee disclosure before you commit.
Use the MAS Financial Institutions Directory to check the firm, and the Register of Representatives to check the individual adviser, both on the MAS eServices site. Every firm giving financial advice must hold a financial adviser's licence or be an exempt financial adviser, and every representative has a unique registration number. If a person or firm is not on the register, do not proceed. This check takes a couple of minutes and is the single most important thing to do before engaging anyone.
A tied agent represents one financial institution and can only recommend that company's products. An independent financial adviser, or IFA, can compare and recommend products from many providers, which widens your options, but they are often still paid by commission from the products you buy. A fee-only adviser charges you directly for advice and rebates any product commissions, which removes the incentive to recommend high-commission products and gives the cleanest position on conflicts of interest. More independence and a fee-only model generally mean advice more aligned with your interests.
A one-off, fee-only comprehensive financial plan typically costs around S$2,000 to S$8,000 depending on complexity, while ongoing wealth management is usually charged as roughly 0.5 to 1 percent of the assets managed each year. Commission-based advice has no direct fee to you, but you pay for it indirectly through the charges built into the products recommended. For a larger or complex situation, paying a fee directly often works out better value than commission because it removes product bias, but the right model depends on your circumstances.
Expats generally need cross-border expertise that ordinary advisers lack, covering things like foreign tax obligations, UK or other overseas pensions, and moving between jurisdictions. Firms that specialise in this include Ascenta Wealth, which works on a fee-based model, GFC for UK pension transfers, and the expat divisions of larger firms like IPP and PromiseLand. Look for an adviser who understands your home country's rules as well as Singapore's, is transparent about fees, and, as always, is MAS-licensed, which you can verify on the directory.
Anyone searching for financial advisers in Singapore is being careful, and they will check whether you look legitimate before they pick up the phone.
Licence details, named people with real faces, plain explanations instead of jargon. Financial firms lose enquiries to sites that feel anonymous, because being anonymous is exactly what the reader is worried about. I build websites for Singapore finance and advisory firms that make the credentials easy to verify, and the SEO to reach people at the moment they start looking.
If your site was built once and never touched again, get a quote and I will tell you what is costing you enquiries.
The best financial adviser in Singapore is a licensed one whose payment model suits you, so verify the firm and adviser on the MAS directory first, then decide between commission, fee-based and fee-only. Providend leads for conflict-free fee-only advice, Financial Alliance for independent scale, and Ascenta or GFC for expats. Read the written recommendation and the fees before you sign anything.
Good advice, from someone whose incentives line up with yours, is one of the better investments you can make. This guide is general information, not financial advice.
If you run a financial or professional-services business and your website is not bringing in enquiries, that is what I do. I design websites for businesses across Singapore. Get in touch for a free consultation.