Terris Recommends 16,400+ monthly visitors Pets
5 Best Pet Insurance Plans in Singapore (September 2026)
The 5 pet insurance plans actually sold in Singapore in 2026, real premiums, and the enrolment age rule that decides whether yours pays out at all.
This guide is part of Terris Recommends, my researched, hands-on picks of the best local businesses and services in Singapore. Every recommendation is researched and ranked by me.
See all recommendationsMost comparison pages for pet insurance Singapore owners can buy rank plans on premium and annual limit. Both matter, but neither is the thing that decides whether your policy pays out when it counts. That is the enrolment age clause, and it is usually three lines deep in a policy document nobody reads until they need to.
Here is why it matters. The conditions that actually bankrupt pet owners here are hereditary ones: hip and elbow dysplasia, luxating patella, intervertebral disc disease, cherry eye, glaucoma. Those are covered by some policies only if the pet was under six years old when the first policy year started, and then only after a further 12-month wait. Buy at seven, and the exact thing your breed was always going to get is the thing you are not covered for.
Singapore's own Animal and Veterinary Service makes the same point in its guidance, which is that you should enrol while your pet is young because most insurers cap enrolment age. Below are the five plans genuinely sold here, what each is best at, and what they cost.
Four things, in the order that actually costs you money.
- Enrolment age and the hereditary clause, together. These two work as a pair and are the whole game. A typical structure covers specified hereditary and congenital conditions only if the pet is below six at the start of the first policy year, after a 12-month waiting period, and provided they were not already showing. The specified list usually includes hip and elbow dysplasia, luxating patella, glaucoma, cherry eye, intervertebral disc disease and femoral head and neck excision. That is a list of the most common serious problems in popular Singapore breeds. AVS advises enrolling while pets are young for exactly this reason.
- Pre-existing means anything already noticed. Every insurer here excludes pre-existing conditions, and the definition is broader than owners expect: it can catch something noted in a vet record before the policy started, even if it was never formally diagnosed. If your pet has any history at all, ask the insurer in writing how they will treat it before you buy rather than after you claim.
- Read the limits as a structure, not a number. A headline annual limit tells you little on its own. What matters is whether there is also a per-condition cap, a per-item sub-limit for the specific treatment your pet needs, and whether surgical and chemotherapy cover sit inside or outside the annual figure. Two policies with the same annual limit can pay out very differently on the same illness.
- Check the breed exclusions if you own a large or bull-type dog. Policies here commonly exclude Mastiffs, Bull Terrier, Staffordshire Bull Terrier, Pit Bull Terrier, American Pit Bull Terrier, Dogo Argentino, Presa Canario, American Bulldog, crosses of those, and any dog crossed with a wolf. If your dog is on that list, confirm before paying anything.
One structural point about this market that no comparison page mentions. Singapore has very few pet insurers, and the brands do not all map to separate underwriters. Aon Happy Tails is underwritten by Income, so comparing the two is not getting two independent views of your pet. When a market is this small, the real choice is narrower than the number of logos suggests.
This is general information about how these products work rather than insurance advice. Policy terms change, and AVS itself recommends contacting insurers directly for current terms and reading the full policy document including all exclusions.
| Plan | Strongest at | Notable feature | Indicative cost |
|---|---|---|---|
| Tiq by Etiqa | Surgical cover | Up to S$15,000 surgical on top tier | Mid to upper |
| MSIG PawEasy | Customisation | Chemotherapy add-on, boarding, acupuncture | Budget to mid |
| Liberty PetCare | Published pricing | No-claim discount up to 15%, wellness benefit | S$392.40 to S$1,471.50 |
| Income Happy Tails | High limits | Separate dog and cat products | Mid to upper |
| CIMB My Paw Pal | Simplicity | Straightforward single product | Budget to mid |
Five entries, not the ten you will see elsewhere, because five is roughly what this market actually contains once you account for shared underwriting. Padding the list with rebadged versions of the same policy would make it look more useful and be less so.
The arithmetic is worth spelling out. A cruciate ligament repair, a foreign body removal or spinal surgery for a disc problem can run several thousand dollars each at a Singapore specialist practice, and a serious case can involve more than one procedure. A policy with a low surgical sub-limit will cover the consultations and the medication perfectly well and then stop exactly where the bill gets large, which is precisely backwards.
Being digital-first, quoting and claiming are done online, which suits people who would rather not deal with an agent. Etiqa's Singapore site blocks automated access, so there is no screenshot below, and you should get your specific quote directly from them since online pricing here changes more often than the annual products.
- Best known for
- Covering the bill that actually hurts
- Underwriter
- Etiqa
- Surgical cover
- Up to S$15,000 on the highest tier, the market high
- Buying
- Digital-first, quote and claim online
- Website
- tiq.com.sg
Two of those extras are worth real money. Chemotherapy is available as an add-on with a lifetime limit of either S$3,000 or S$6,000, which matters because cancer treatment is one of the few things that will exhaust a standard annual limit on its own. Pet boarding cover is the other one people overlook: if you are hospitalised or stuck overseas, the cost of boarding an animal for a fortnight is real, and very few policies address it at all.
It also covers acupuncture and complementary therapy and offers pet mobility aids, which is unusual and relevant for older or post-surgical animals. MSIG also sells a separate Silversky Protect plan, so if PawEasy does not fit, ask them to quote both rather than assuming the one you found first is their only product.
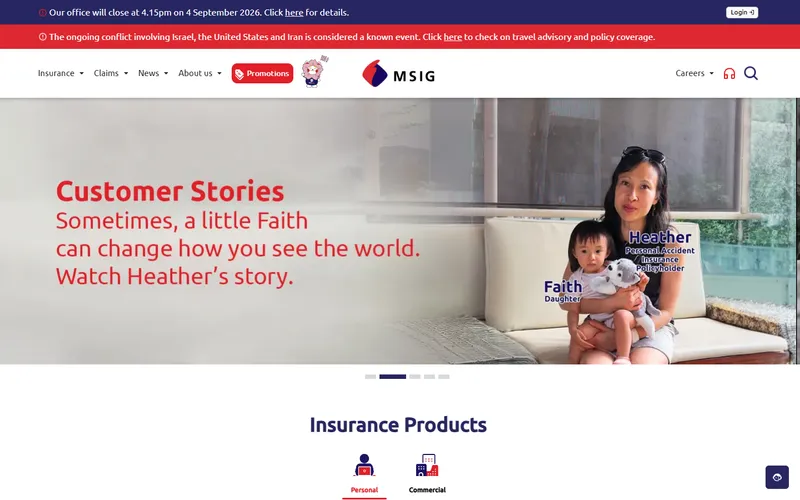
- Best known for
- Adequate cover without paying for the rest
- Structure
- Modular, pay only for the add-ons you want
- Chemotherapy
- Optional add-on, S$3,000 or S$6,000 lifetime limit
- Unusual inclusions
- Pet boarding, acupuncture, mobility aids
- Website
- msig.com.sg
Two features stand out. There is a no-claim discount of up to 15%, which over several quiet years is a meaningful reduction and is rare in this market. And the top three tiers include a wellness benefit with an annual limit of S$100 to S$200, which does not sound like much until you remember that routine care is excluded almost everywhere else, so any wellness allowance at all is unusual.
The enrolment window is stated plainly: from 8 weeks old up to below 9 years. That upper bound is the clearest illustration of the timing point in this whole guide. One note for anyone searching: Liberty's old Singapore address now redirects to libertyinternational.com, and its site would not respond to automated capture, which is why there is no screenshot below.
- Best known for
- Publishing its prices, and the wellness benefit nobody else gives
- Premiums
- From S$392.40/year, top Pawsh plan S$1,471.50
- Enrolment age
- 8 weeks to below 9 years
- No-claim discount
- Up to 15%
The strength here is high annual and lifetime limits for surgical and chemotherapy treatment, which puts it in the same conversation as Tiq for the serious end of the risk. If you are insuring a breed with a known predisposition to something expensive, the limits are the section of the brochure to read first, and Income's are among the better ones.
The disclosure worth making: Aon Happy Tails is underwritten by Income. If you have been quoted by both and thought you were comparing two insurers, you were comparing two distribution channels for the same underwriter. That is not a criticism of either, it just means you have fewer genuine options than the search results imply, and you should add a different underwriter to your comparison rather than a second brand of this one.
- Best known for
- Treating cats and dogs as different animals
- Products
- Happy Tails for dogs, Happy Tails Purrfect for cats
- Strength
- High annual and lifetime surgical and chemotherapy limits
- Note
- Also underwrites Aon Happy Tails, so those two are not independent
- Website
- income.com.sg
That suits a specific owner well: someone with a young, healthy, common-breed pet who wants protection against a large unexpected bill and does not want to spend an evening comparing sub-limits. Buy it early, when the enrolment age and hereditary clauses are still working in your favour, and it does the job it is meant to do.
It suits you less if your pet is older, has any history, or belongs to a breed with a known predisposition. In those cases the detail in the limits is exactly what you need to be reading, and one of the more configurable plans above will serve you better. As with everything in this category, take the actual policy wording rather than the product page, since the page summarises and the wording decides.
- Best for
- Young, healthy, common-breed pets
- Best known for
- Being easy to understand before you buy
- Structure
- Single straightforward product
- Less suited to
- Older pets or breeds with known predispositions
- Website
- cimb.com.sg
Pet insurance in Singapore costs from under S$100 a year for accident-only cover to about S$1,470 a year for a top-tier dog plan. Meaningful illness and surgical cover, which is what most owners actually want, starts from roughly S$350 a year for cats and S$600 for dogs. Liberty PetCare publishes premiums from S$392.40 across both species.
Premiums rise with the pet's age, which is the other half of the timing argument. A policy bought at one year old is cheaper than the same cover bought at six, and buying early also secures the hereditary cover that later enrolment may exclude entirely. The cost of waiting is therefore paid twice.
Set that against the bills you are insuring. A single orthopaedic or spinal surgery at a Singapore specialist can run into several thousand dollars, and cancer treatment more again, which is why the surgical sub-limit and any chemotherapy add-on matter far more than a S$50 difference in annual premium.
No. Every pet insurer in Singapore excludes pre-existing conditions, and AVS lists them first among standard exclusions alongside hereditary issues, preventive care such as vaccinations, behavioural conditions and cosmetic procedures. There is no plan on this list or elsewhere in the market that covers a condition your pet already has.
The practical difficulty is the definition. A pre-existing condition is not only something formally diagnosed; it can include signs recorded in a vet's notes before the policy started. An owner who mentioned occasional limping at a routine check two years ago may find a later joint claim declined on that basis.
Two things reduce the risk. Buy while the pet is young and has no history, which is the entire argument of this guide. And if there is any history, disclose it fully and get the insurer's position in writing before the policy starts, because a declined claim eighteen months later is a far worse outcome than a slightly restricted policy bought with open eyes.
I started from the policy mechanics rather than the premium tables, because in this category the premium is the least informative number available. Reading the enrolment age and hereditary clauses alongside each other is what produced this guide's central point, and it is not something a price comparison will ever surface.
I also checked who underwrites what, which is how the Aon and Income overlap surfaced. That kind of thing matters in a market this small: the number of brands is not the number of choices, and a comparison that treats them as independent overstates how much shopping around can achieve.
Two entries have no screenshot. Etiqa's Tiq site and Liberty's site both refused automated access, one with a bot wall and one with a protocol error, so I have said so on those entries rather than leaving a gap. Premiums and limits were what the providers and market showed at the time of writing, and insurers revise these regularly, so follow AVS's advice and confirm current terms directly. None of these links earns me anything.
Buy it now, whatever "it" turns out to be. If your pet is under six and healthy, the enrolment age and hereditary clauses are working in your favour today and will not be in a few years. That timing decision outweighs the difference between any two plans on this page.
On the plans themselves: take Tiq or Income if you want the surgical and chemotherapy limits to hold up in a bad year, MSIG PawEasy if you would rather build a cheaper policy around the specific risks you care about, Liberty if you value published pricing and a no-claim discount, and CIMB if you want one clear product and no evening spent comparing sub-limits.
Whichever you choose, read the actual policy wording and not the product page, and check the breed exclusion list if you own a large or bull-type dog. If you are still assembling the rest of pet ownership, my picks of the best veterinary clinics in Singapore are the natural next stop, along with the best pet grooming salons and, for the times you travel, the best pet boarding and hotels in Singapore.
A closing note on why I write these. I build websites for Singapore businesses, and insurance is the clearest example of a category where the pages that rank are built to earn commission rather than to explain the clause that decides your claim. If your business would rather win by being genuinely useful, take a look at my web design services in Singapore, or get a quote.