Terris Recommends 16,400+ monthly visitors Finance & Insurance
7 Best Renovation Loans in Singapore (September 2026)
The 7 best renovation loans in Singapore for 2026, with real EIRs, the S$30,000 cap explained, and the disbursement rule that quietly limits which contractor you can hire.
This guide is part of Terris Recommends, my researched, hands-on picks of the best local businesses and services in Singapore. Every recommendation is researched and ranked by me.
See all recommendationsMost guides to the best renovation loan Singapore banks offer are rate tables, and a rate table is the least useful part of this decision. I went through the actual product terms instead, and the thing that stood out is not on any comparison page: a renovation loan is never paid to you.
The bank issues cashier's orders made out to your contractor. That single mechanic changes the whole exercise. It means the loan is tied to a specific quotation, it means the money can only buy fixed works, and for an HDB flat it means your contractor has to be on HDB's registered list before the bank will release anything. Your choice of lender quietly constrains your choice of contractor, and nobody mentions it until the paperwork stage.
Below are seven lenders worth considering, split between genuine renovation loans and the personal loans people use instead, with the real effective rates rather than the advertised ones. None of these links earns me anything.
Five things, and the first two are the ones that catch people out.
- The money goes to the contractor, not to you. Unlike a personal loan, which lands in your account as cash, a renovation loan is disbursed as cashier's orders made out to your appointed renovation firm, often in tranches tied to project milestones. DBS caps this at four cashier's orders, with additional ones at S$5 each. If you are managing several trades yourself rather than using one main contractor, count your payees before you pick a lender.
- The ceiling is lower than people expect. Under current rules the limit is the lower of six months' income or S$30,000, and it includes any outstanding renovation loan you already hold with the same bank. On a S$5,000 monthly salary that is S$30,000 against a typical four-room renovation, so treat this as partial financing rather than the budget.
- Fixed works only. Flooring, tiling, plumbing, electrical, false ceilings, carpentry, painting and structural changes qualify. Furniture, appliances, curtains and anything movable do not. People routinely budget the loan for the whole project and then discover the sofa and the fridge are on them.
- Your contractor has to qualify too. For HDB flats, banks will not disburse to a firm that is not in the Directory of Renovation Contractors. Getting listed requires ACRA registration for at least a year, three years of renovation experience and the Renovation for Public Housing course at BCA Academy. That is a real quality filter, and it is being applied to your shortlist by your bank.
- Compare the EIR. The advertised rate excludes fees; the effective interest rate includes them. A typical structure is a handling fee around 2% of the approved amount plus a compulsory insurance premium of about 1%, both taken off the top. That is why a 5.08% headline becomes a 6.16% EIR, and why one product on this list advertises around 5.42% while its EIR sits near 10.96%.
Worth knowing on the regulatory side: renovation borrowing sits inside your overall unsecured limit, and the Monetary Authority of Singapore frames total unsecured credit against your annual income while lenders assess your total monthly debt servicing. If you are already carrying a car loan and a credit card balance, that is what decides your approval, not the renovation quote. MoneySense is the government's own free guidance on this, and it is genuinely good.
This is general information about how these products work, not financial advice. Your circumstances decide what is sensible, and the bank's current terms always override anything written here.
| Lender | Type | Indicative rate | Indicative EIR | Paid to |
|---|---|---|---|---|
| DBS | Renovation loan | 3.38% promo, 5.08% standard | 4.49% promo, 6.16% standard | Contractor |
| OCBC | Renovation loan / ExtraCash | From ~5.42% | ~10.96% | Contractor |
| Maybank | Renovation loan | From ~2.50% year one | Reverts after year one | Contractor |
| Standard Chartered | Personal loan (CashOne) | From ~0.90% | From ~1.75% | You |
| HSBC | Personal instalment plan | Varies by tenure | Stated per plan | You |
| CIMB | Personal loan | Varies by tenure | Stated per plan | You |
| UOB | Personal loan | Varies by tenure | Stated per plan | You |
Two cautions on that table. Rates in this category change monthly and promotions come and go, so treat these as the shape of the market and check the bank's own page before applying. And the last column is the one that actually sorts the list: the top three restrict what the money can buy and who it can be paid to, while the bottom four hand you cash and let you spend it on the sofa.
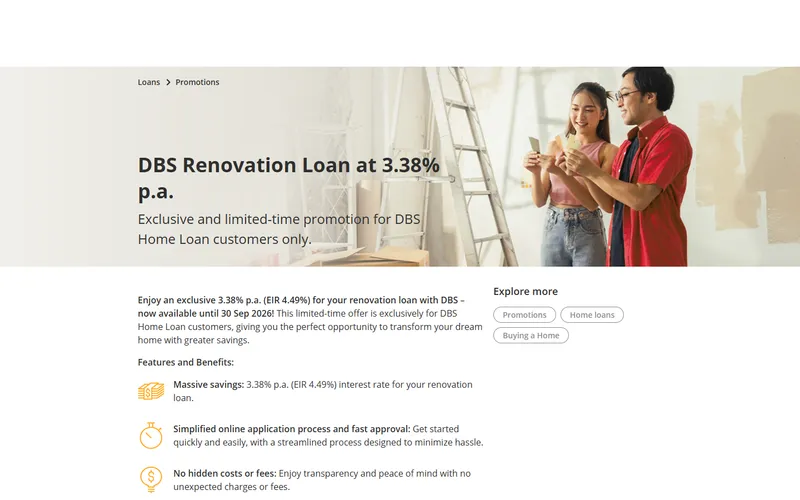
Outside the promotion the standard product is 5.08% p.a. at an EIR of 6.16%, with an eco-aware variant at 4.88% (EIR 5.96%) for qualifying energy-efficient works. The gap between the advertised rate and the EIR is explained rather than hidden: a handling fee of 2% of the approved amount and an insurance premium of 1%, both deducted up front. Tenure runs to five years and the cap is the usual six times monthly income or S$30,000, whichever is lower.
The documentation is standard and worth preparing in advance: a signed invoice or quotation from your contractor, income documents, proof of ownership (waived if you hold a DBS or POSB home loan) and the HDB or MCST renovation permit where one is needed. Disbursement is by cashier's order to the contractor, with a maximum of four issued and extras at S$5 apiece.
- Best known for
- The clearest terms in the category, and the best rate if you bank your mortgage here
- Promo rate
- 3.38% p.a. (EIR 4.49%) for DBS home loan customers, until 30 Sep 2026
- Standard rate
- 5.08% p.a. (EIR 6.16%); eco-aware 4.88% (EIR 5.96%)
- Fees
- 2% handling, 1% insurance premium
- Website
- dbs.com.sg
The cost is the catch. Indicative pricing has run from around 5.42% p.a. with an effective interest rate near 10.96%, which is roughly double the headline. That is the widest advertised-to-effective gap I found among the mainstream lenders, and it is exactly the situation the EIR figure exists to expose. If you compare OCBC to DBS on the advertised numbers they look close. On EIR they are not close at all.
Where it earns its place is speed and eligibility. If your income sits below what the other banks want, or the contractor needs a deposit this week and the alternative is a credit card at over 25%, this is the cheaper problem. Just go in knowing the real rate. OCBC's renovation loan page is script-driven and would not render for automated capture, which is why there is no screenshot below.
- Best known for
- Getting approved quickly when other banks say no
- Indicative rate
- From around 5.42% p.a., EIR near 10.96%
- Income floor
- From about S$20,000 a year
- Speed
- Instant approval and disbursement via Myinfo
- Website
- ocbc.com
That structure is not dishonest, it is just easy to misread. A teaser rate on a five-year loan means one cheap year and four at the reverted rate, so the number that matters is the blended cost across the full tenure rather than the figure in the advertisement. Ask for the total repayable across five years and compare that against DBS's flat 5.08%, and the ranking often changes.
It can still be the right answer, particularly if you expect to repay early, though check the early redemption terms before assuming that. Maybank's site returned a protocol error to automated access on repeated attempts, so there is no screenshot below and I would encourage checking the current terms directly rather than trusting any third-party rate table, this one included.
- Best known for
- The lowest advertised rate, with the most conditions attached
- Indicative rate
- From around 2.50% in year one, reverting from year two
- Watch for
- The blended cost across the full five years
- Ask about
- Early redemption terms
- Website
- maybank2u.com.sg
The reason it can be cheaper and still make sense for the bank is that a personal loan is priced on you rather than on the security of a fixed-works quotation. What you gain is freedom: the money arrives in your account, so it can pay for the sofa, the fridge, the curtains and the contractor, with no cashier's orders, no quotation to submit and no requirement that your contractor sits on any register. For anyone renovating a condo, or paying several small trades directly, that flexibility is worth real money.
Two things to check. Long-tenure headline rates usually assume the longest term, which means more total interest even at a lower rate, so run the total repayable rather than the percentage. And a personal loan uses up the same unsecured borrowing headroom, so taking one may affect a mortgage application later.
- Best known for
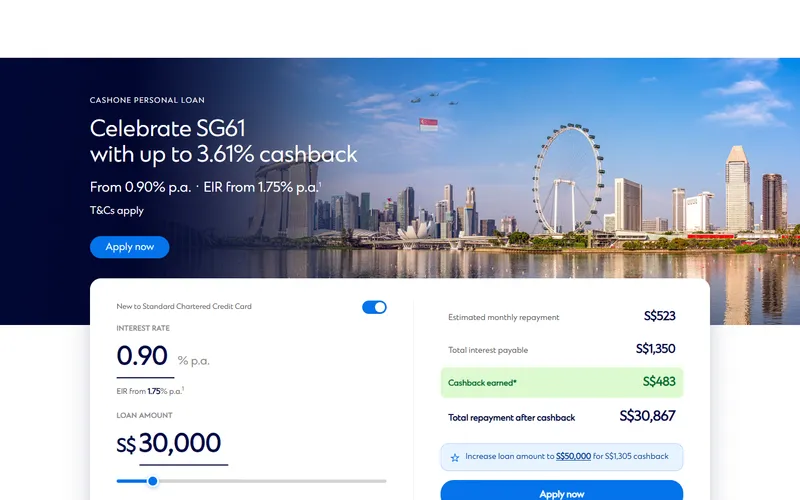
- The cheapest way to fund a renovation if you want the cash
- Type
- Personal loan, paid to your account
- Indicative rate
- From around 0.90% p.a., EIR from about 1.75%
- Covers
- Furniture and appliances, which renovation loans do not
- Website
- sc.com/sg
What makes it worth a quote is that pricing in this category is heavily relationship-driven and promotional. The rate a bank shows a new customer and the rate it shows someone who already holds an account there can differ enough to change the ranking, which is why getting two or three quotes beats reading two or three comparison tables. It costs you nothing but an afternoon.
The same caution applies as with any personal loan used for renovation: the flexibility is real, but so is the fact that you are converting a secured-feeling purchase into unsecured debt. Borrow the amount the quotation actually needs rather than the amount you are approved for.
- Best known for
- Being worth a second quote when you already bank here
- Type
- Personal instalment plan, paid to your account
- Rate
- Varies by tenure, EIR stated per plan
- Worth doing
- Ask for the existing-customer rate
- Website
- hsbc.com.sg
It is a smaller bank here, and that cuts both ways. The branch network is thin compared with the local three, so if you like sorting money matters in person this is not the one. If you are content to do everything online, the trade is usually a slightly better rate for slightly less hand-holding.
As with the other personal loans on this list, the money reaches your account rather than your contractor, so it covers the whole project including the parts a renovation loan will not touch. Compare the total repayable against a renovation loan's total, including that 2% and 1% deducted at the start, before deciding which is actually cheaper.
- Best known for
- Straightforward terms without the footnote maze
- Type
- Personal loan, paid to your account
- Strength
- Transparent pricing and flexible repayment
- Trade-off
- Fewer branches than the local three
- Website
- cimb.com.sg
That is worth knowing because a lot of comparison articles list a UOB renovation loan anyway, carried over from older content, and you can lose an afternoon looking for a product that is not being sold. If you bank with UOB and want renovation financing, the conversation is about a personal loan, with everything that implies: cash to your account, no contractor restriction, no quotation required, and pricing set on your profile rather than on the works.
Given the relationship pricing point above, it is still worth asking UOB for a quote if your salary is credited there. Just ask for the personal loan by name, compare the total repayable rather than the rate, and hold it against the DBS promotion if you happen to qualify for that.
- Best known for
- Being the local bank people wrongly assume has a renovation loan
- Type
- Personal loan; no dedicated renovation loan currently listed
- Paid to
- Your account
- Worth doing
- Ask for a quote if your salary is credited here
- Website
- uob.com.sg
A renovation loan in Singapore is capped at the lower of six times your monthly income or S$30,000, across every major bank, with a maximum tenure of five years. On a S$5,000 monthly salary the six-times figure is S$30,000, so the cap binds for most applicants. Any renovation loan still outstanding with the same bank counts against that ceiling.
Set against a typical four-room HDB renovation, that is partial financing rather than the whole budget, which is the planning point most people miss. The realistic structure is cash or CPF for part of the job, a renovation loan for the fixed works, and separate provision for furniture and appliances, which the loan will not cover.
Your approval also depends on borrowing you already carry. Renovation debt sits within your overall unsecured credit position, so an existing car loan, credit card balance or personal loan reduces what a bank will extend, regardless of how modest the renovation quotation is.
A renovation loan is usually cheaper on rate, and a personal loan is usually more useful. Renovation loans price lower because the bank controls where the money goes, disbursing by cashier's order against a contractor's quotation for fixed works only. Personal loans cost more in principle but arrive as cash you can spend on anything, including the furniture and appliances a renovation loan excludes.
In practice the gap has narrowed enough that the comparison is worth running properly. Some personal loan promotions here advertise effective rates below the renovation loans, and once you add a renovation loan's 2% handling fee and 1% insurance premium deducted up front, the supposedly cheaper product is not always cheaper.
My rule of thumb: if you are using one main contractor on a registered list, doing mostly fixed works, and one of the renovation loan promotions applies to you, take the renovation loan. If you are paying multiple trades directly, buying a lot of furniture, or renovating a condo where the DRC requirement does not apply, take the personal loan and enjoy not managing cashier's orders.
I read the banks' own product pages and terms rather than the comparison sites, because this is a category where affiliate tables go stale and quietly keep listing products that no longer exist. That is how I found that one of the local three has no renovation loan on its pages at all, while plenty of current articles still list one.
Rates here are indicative and were what the lenders were showing at the time of writing. This category re-prices constantly and runs limited promotions, the DBS offer being a live example with an end date on it, so please check the bank's own page before applying rather than treating any table, mine included, as current.
Two entries have no screenshot: OCBC's renovation loan page is script-driven and renders blank to automated capture, and Maybank's site returned a protocol error on repeated attempts. I have said so on those entries rather than leaving an unexplained gap. Nothing here is paid placement and none of these links earns me a commission, which is worth saying in a category where most comparison pages are monetised on exactly that basis.
If you hold a DBS home loan, take the 3.38% promotion before it closes on 30 September 2026. Nothing else here comes close and the condition is one you either meet or do not. Failing that, the honest answer for most people is to get one renovation loan quote and one personal loan quote and compare the total repayable across the full tenure, because the ranking genuinely flips depending on fees and promotions in any given month.
Do the sequencing in the right order, though. Work out your contractor shortlist and get a proper itemised quotation first, because the loan is written against that quotation, and for an HDB flat the bank will check the firm is on the Directory of Renovation Contractors before releasing a cent. My picks of the best renovation contractors in Singapore and the best interior design firms in Singapore are the place to start, and if you are working to a property type there are dedicated shortlists for HDB BTO and resale HDB flats.
And budget separately for everything the loan will not buy. The flooring and the carpentry are financed; the sofa, the fridge and the curtains are not. If you are furnishing at the same time, my picks of the best furniture shops in Singapore and the best lighting shops in Singapore cover the part of the budget people forget until the keys are in hand.
One note on why I write these guides. I build websites for Singapore businesses, and I keep noticing that the pages ranking for financial terms are mostly built to earn a commission rather than to answer the question. If your business would rather rank by being genuinely useful, take a look at my web design services in Singapore, or get a quote.